Business interruption indemnity period: choosing the right length
The fire assessor finishes his walk-through of your Germiston warehouse on a Thursday afternoon, closes his notebook, and tells you the rebuild will take fourteen to sixteen months. You nod, relieved that the damage policy is in order, and only later that evening, sorting through the policy schedule on the kitchen table, do you notice the figure printed next to "maximum indemnity period": twelve months. Everything after month twelve is your income to replace, your salaries to fund, and your fixed costs to carry. The policy wasn't wrong. The number chosen at inception simply wasn't the number your business needed.
What is indemnity period insurance?
The indemnity period in business interruption insurance is the maximum length of time the insurer will replace your lost income after a covered event. It starts on the date of the loss, the fire, the flood, the riot, and stops on the date the policy names, whether your trading has recovered by then or not. The period isn't how long repairs take; it is how long your cover lasts.
Key Takeaways
- The indemnity period is a choice made at inception, and most businesses set it once and never revisit it.
- A period set too short leaves you funding your own recovery from the point it expires, even while the cause of the interruption is still present.
- Fourteen to twenty-four months is the realistic recovery window for most mid-sized South African commercial operations after a significant loss event.
- Business interruption cover and the underlying material damage policy must align: most BI wordings only respond if the physical damage is covered under the property section.
- SASRIA (the state-owned special-risks insurer covering riot and civil unrest damage) issues its own business interruption endorsement, and its period must match your standard BI policy's period to avoid a gap between them.
- Extending the period at renewal costs a fraction of what carrying the tail-end exposure yourself costs at claim time.
Why the standard twelve-month period leaves most businesses exposed
The twelve-month indemnity period became the industry default not because it reflects how long businesses take to recover, but because it was the figure keeping premiums manageable when brokers were quoting in a hurry. Most commercial policyholders accepted it without question, the same way terms and conditions get read: once, at speed, with one hand already reaching for the pen.
Twelve months sounds substantial. In practice, the clock runs faster than you expect. A significant fire at a food-processing plant in the Western Cape typically triggers a loss-adjustment process consuming the first two to three months before a repair contractor is even appointed. Add six to nine months of active rebuild. Add the time needed to restart production, retrain staff who have dispersed, and recertify machinery. Add the months spent winning back the retail buyers who sourced elsewhere while you were dark. Eighteen months of genuine income interruption against twelve months of cover isn't a worst-case scenario; it is a common one. SASRIA's own business interruption wording makes clear that the BI cover it provides responds to loss at insured premises during the period the policy names, which means any gap between what the wording allows and what recovery takes falls on the insured's account.
The industry calls the tail-end exposure "the uninsured period", but that phrase is too clean. It isn't a separate event. It is the last chapter of the same loss, carrying the same fixed costs and the same absent revenue, with no policy responding to any of it.
How to calculate the indemnity period your business needs
Choosing the right indemnity period requires answering three questions in sequence, not guessing at a round number.
First question: how long does the physical rebuild take? This isn't your architect's best-case estimate. It is the realistic timeline assuming municipal approvals, contractor availability in your region, and the lead times for the specialist equipment your operation uses. A manufacturing plant using imported German tooling should budget twelve to eighteen months for equipment lead times alone. A retail space in a well-serviced Johannesburg suburb might genuinely rebuild in six. The answer to this question sets the floor for your indemnity period, not the ceiling.
Second question: how long does revenue recovery take after reopening? Revenue doesn't return on the day the doors open. Customers have moved on, contracts have lapsed, and your sales pipeline is empty. In business interruption claims, this revenue-recovery tail is the part of the loss most often underestimated. For businesses with long-term client relationships and repeat-order cycles, the tail can run six to twelve months beyond physical restoration.
Third question: does anything in your wording limit the period? Most wordings carry a material damage proviso, meaning the business interruption claim only responds if the physical damage is covered under the property section. Some also end the cover once the loss no longer results from the original damage. Check both with your broker before assuming the full period is available to you in every scenario.
Add the answers to the first two questions. That total is your minimum indemnity period. Round up to the next policy increment and then consider what a further six months of cover costs, because that premium is almost always less than one month of your fixed overhead.
The indemnity period and the SASRIA alignment problem
SASRIA, the state-owned insurer created specifically to cover riot, strike, and civil unrest damage in South Africa, issues its business interruption endorsement alongside the standard material damage coupon. The arrangement works as follows: your commercial insurer collects the SASRIA premium on SASRIA's behalf, and SASRIA responds to the interruption caused by a covered unrest event. What the arrangement doesn't do automatically is match the SASRIA BI period to your standard BI policy's period.
If your standard policy carries a twenty-four-month indemnity period and your SASRIA endorsement carries a twelve-month period, a riot burning your factory creates two different cover timelines for the same loss. Months one through twelve are covered under both. Months thirteen through twenty-four are covered under your standard policy but not under the SASRIA endorsement, and the split is consequential because the trigger event was an unrest peril, not a fire peril. Whether your standard wording responds to a SASRIA-triggered loss in months thirteen through twenty-four is a question your broker needs to answer before the claim, not during it. SASRIA's business interruption endorsement specifies the period in the schedule, and that figure needs deliberate alignment with your primary BI cover at renewal.
The practical fix is straightforward: request matching periods across both policies at every renewal, and document the instruction to your broker in writing.
How the indemnity period interacts with your gross profit sum insured
The indemnity period and the gross profit sum insured aren't independent choices. They work together, and underestimating one compounds the effect of underestimating the other.
Gross profit in a BI policy isn't the accounting net profit figure most business owners have in mind. It is the revenue the business generates after deducting the costs genuinely ceasing when trading stops, raw materials, for instance, but before deducting the fixed costs continuing regardless, such as salaries, rent, and loan repayments. The sum insured should represent the gross profit the business would have earned during the full indemnity period. An indemnity payment replaces what the business would have earned, which is why the gross profit figure and the period must reflect a realistic projection rather than last year's numbers.
Illustrative example: suppose your business earns R6 million in annual gross profit and you carry a twelve-month indemnity period. Your sum insured should be R6 million. If the same business carries a twenty-four-month period, the sum insured should be R12 million. If you set the sum insured at R6 million and then claim under a twenty-four-month period, the insurer applies the average clause, the same arithmetic applying to underinsured property, and the payout is halved. The missing R6 million isn't a rounding error. It is the difference between surviving the interruption and not.
These figures are illustrative teaching examples, not market rates or guaranteed outcomes.
| Indemnity period | Annual gross profit | Correct sum insured | Underinsured at (example) | Average clause shortfall |
|---|---|---|---|---|
| 12 months | R 6 000 000 | R 6 000 000 | R 4 000 000 | R 2 000 000 claim pays R 1 333 000 |
| 18 months | R 6 000 000 | R 9 000 000 | R 6 000 000 | R 2 000 000 claim pays R 1 333 000 |
| 24 months | R 6 000 000 | R 12 000 000 | R 8 000 000 | R 2 000 000 claim pays R 1 333 333 |
Illustrative comparison: average clause impact at different indemnity period and sum insured combinations. All figures are for teaching purposes and do not represent market rates or insurer calculations.
Sectors where a longer indemnity period is non-negotiable
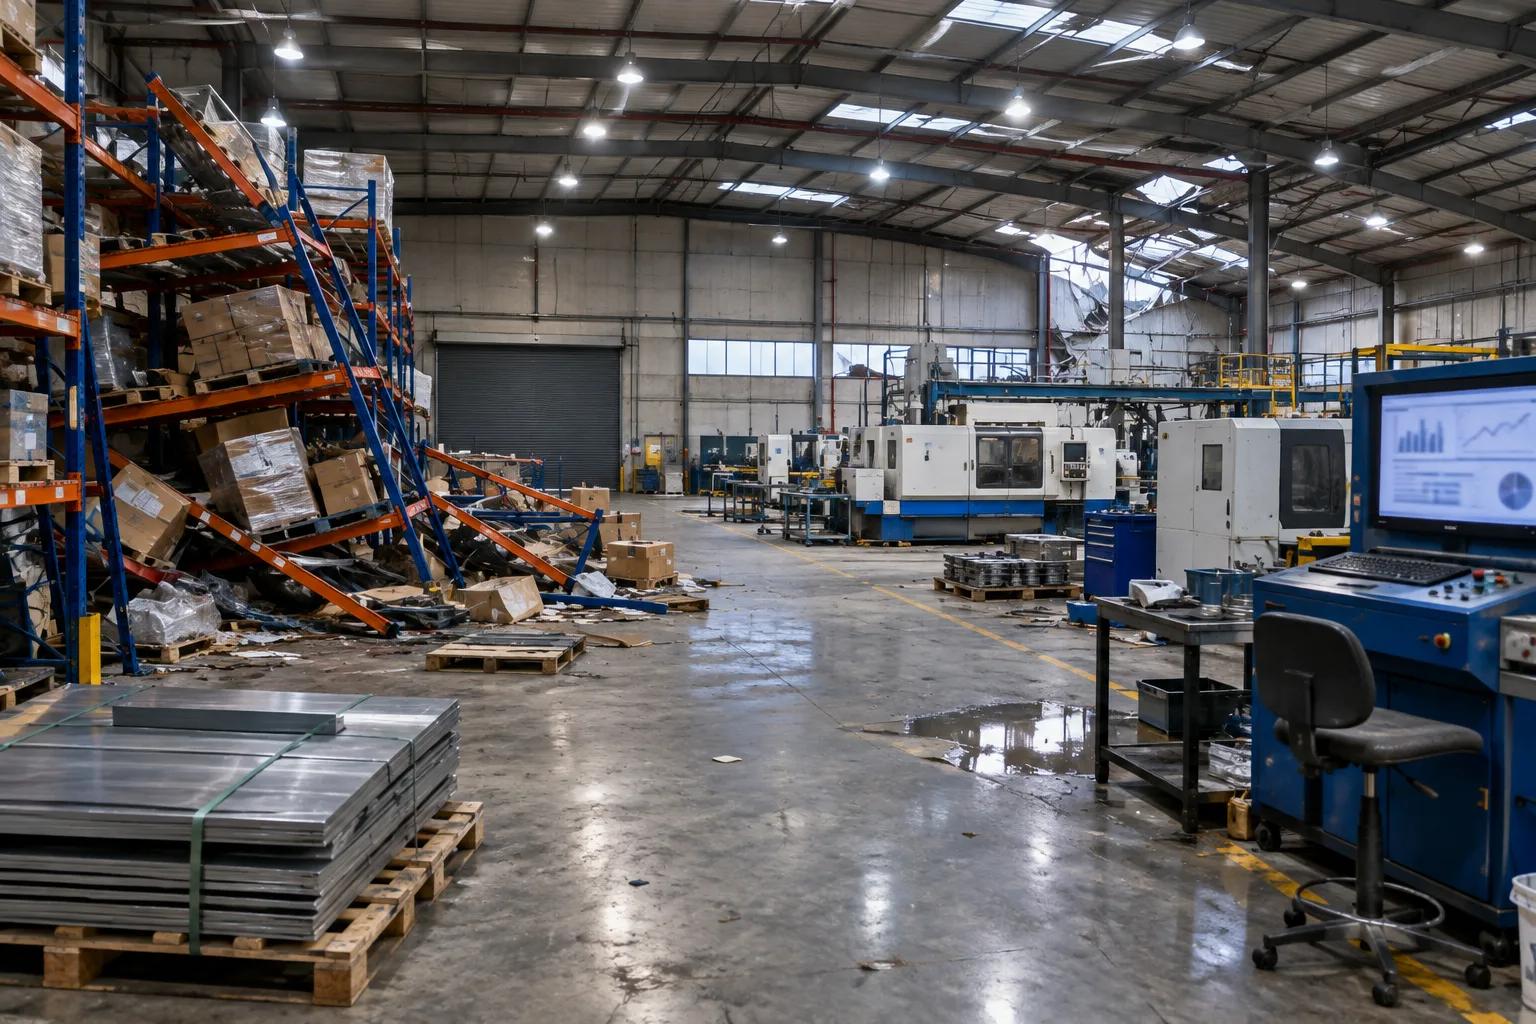
Some industries have structural recovery timelines making anything shorter than eighteen months a genuine exposure. Knowing where your sector sits should inform the conversation at renewal before an underwriter's default choice does it for you.
Manufacturing with specialised plant. A business relying on custom-built or imported machinery, packaging equipment, injection moulding lines, industrial bakery plant, faces lead times of six to twelve months for replacement equipment alone, before installation, commissioning, and the production ramp-up following. The insurance policy schedule must reflect the actual plant and its replacement lead times for the cover to respond correctly, and the same applies to the indemnity period chosen for that plant.
Agricultural processing. A citrus packhouse or a wine estate operates in strict seasonal cycles. A fire in March, at the start of the packing season, means an entire season's revenue is lost before a single repair is completed. The indemnity period must span at least two full seasons to provide meaningful cover, because the first season's revenue can't be recovered; it is gone.
Professional services with long client cycles. An engineering consultancy or a specialist legal practice rebuilds its fee income slowly. Clients retained on annual mandates may not return at all after an interruption. The indemnity period needs to reflect not the cost of the office rebuild, but the time required to rebuild the client book, which is rarely less than eighteen months.
Businesses in high-risk unrest areas. South African businesses in areas with an elevated SASRIA risk profile should treat a twenty-four-month indemnity period as the starting point, not the maximum, given that unrest events often affect entire supply chains and distribution networks simultaneously, extending recovery timelines beyond what a single-site fire would cause.
What reviewing your indemnity period at renewal involves
Most renewals go like this: the broker sends the schedule, you check the premium, you approve the debit order, and the policy rolls over unchanged from the previous year. The indemnity period chosen in 2021 runs in 2026 on a business grown, moved premises, added machinery, and signed contracts with revenue implications the 2021 schedule doesn't reflect.
A genuine indemnity period review takes thirty to sixty minutes and covers four things: whether the rebuild timeline has changed (a new building, a new production line, a different municipality with a different approval process); whether the revenue recovery tail has changed (new customers, longer contracts, a market more competitive); whether the gross profit sum insured still reflects current trading at the period chosen; and whether the SASRIA BI period has been aligned to the standard BI period.
Business interruption cover works as the financial bridge between the event and the recovery. The bridge needs to be long enough to reach the other side. The FSCA's conduct framework for short-term insurers places the obligation on the insurer and the intermediary to ensure the product sold is appropriate for the client's risk profile, but it can't substitute for a client who has thought through what their recovery looks like.
The cost of getting it right versus the cost of getting it wrong
The premium difference between a twelve-month and a twenty-four-month indemnity period, on a typical mid-sized commercial risk, is between ten and twenty percent of the BI premium component alone. The BI premium is a fraction of the total commercial package premium. On a policy with a total annual premium of R180 000, the BI component might be R40 000, and the difference between twelve and twenty-four months might cost R6 000 to R8 000 a year more. These figures are illustrative estimates for teaching purposes and do not represent market rates or guaranteed outcomes.
The cost of carrying six months of uninsured interruption on a business generating R6 million in annual gross profit is approximately R3 million in lost income, before fixed costs already committed. The arithmetic doesn't require a calculator. It requires a conversation at renewal most policyholders have never had, because nobody asked the question.
That conversation starts with a simple question: if your main premises were out of action tomorrow, how long would it realistically take to rebuild, re-equip and win back your customers? The answer is the starting point for your indemnity period.
The clock you set before the fire
The indemnity period is one of those choices feeling theoretical until it is the only number on the page counting. It sits in the schedule without fanfare, next to the sum insured and the excess, and gets renewed on the same figure year after year because changing it requires a decision, and decisions require information nobody thought to gather. The businesses recovering fully from a significant interruption are rarely the luckiest ones. They are the ones whose broker asked the right question at the last renewal, the answer got written down, and the period was long enough to reach the other side.
You shouldn't have to discover what your indemnity period was set to by reading the schedule in the same week the repair contractor gives you a timeline. With Mont Blanc Financial Services you won't.
Contact Mont Blanc Financial Services to review your current business interruption cover, align your indemnity period to your actual recovery timeline, and make sure the sum insured and the period are working together before a claim tests them separately.
Business interruption insurance raises more detailed questions than most policyholders expect, and the indemnity period is usually where those questions start. The most common ones are answered below.
Frequently Asked Questions
What does indemnity period insurance mean in business interruption cover?
The indemnity period in business interruption insurance is the maximum number of months the insurer will pay your lost gross profit and continuing fixed costs after a covered event. It begins on the date of the loss and ends on the date stated in your policy schedule, regardless of whether your business has fully recovered by then. It isn't the same as the repair period: repairs might finish in eight months while your revenue takes sixteen months to return to pre-loss levels. The gap between those two timelines is the exposure most businesses underestimate when they accept a standard twelve-month period at inception. Choosing the right indemnity period insurance length means estimating three things honestly: how long the physical rebuild takes, how long the revenue recovery takes after reopening, and whether your gross profit sum insured reflects the full period chosen. Getting the period right is a question of arithmetic and judgment before the event; getting it wrong is a question of survival after it.
What are common exclusions in indemnity period cover for business interruption?
Standard business interruption wordings exclude several categories of loss even within the indemnity period, and understanding them before a claim saves the particular misery of discovering them during one. The most common exclusions in South African commercial BI wordings are: losses arising from perils not covered by the underlying material damage policy (if the physical trigger is excluded, the BI claim falls away with it); losses caused by riot and civil unrest, which are covered separately under SASRIA and require a matching SASRIA BI endorsement; losses where the interruption has no direct physical damage trigger at the insured's own premises (contingent BI, where a supplier or a key customer suffers the damage, is usually excluded unless specifically added); and losses continuing past the point at which the business could reasonably have resumed trading, even if the physical repairs aren't yet fully complete. Some wordings also include a clause ending the indemnity period when the loss no longer directly results from the original damage event. Your broker should walk through each of these with you before renewal, not after a claim is submitted.
How is the indemnity period different from the policy period?
These two periods are unrelated but are frequently confused, often at the worst possible time. The policy period is the twelve-month window during which your insurance contract is in force: the year from one renewal date to the next. The indemnity period is a sub-clause inside the business interruption section of that policy, naming the maximum duration of BI payments following a single covered loss. A policy with a twelve-month policy period can carry a twenty-four-month indemnity period without contradiction: the loss simply needs to occur during the policy year, and the BI cover then responds for up to twenty-four months from the date of that loss, even if the indemnity period runs into the following policy year. Conversely, a twenty-four-month policy period paired with a twelve-month indemnity period gives you a long contract but short cover for any individual interruption event. The indemnity period is the number governing recovery. The policy period governs when a loss must occur to be covered at all.
How often should a business review its business interruption indemnity period?
At least once a year, at renewal, and whenever the business changes in a way that would affect how long recovery would take. Examples include moving to new premises, adding specialised machinery with long lead times, taking on a major contract, or relying more heavily on a single supplier or customer. Building and equipment costs, and the time contractors need, can also change from year to year, which may lengthen a realistic rebuild timeline. A useful review starts with your own recovery plan: how long it would take to find or rebuild premises, replace equipment, restore stock and regain customers. Compare that estimate with the indemnity period on your schedule. If the estimate is longer, discuss extending the period with your broker, and ask what the change would cost in premium compared with the income it would protect. Keep a note of each review and the reasons for your decision.
Nicola Iozzo
Founder & CEO, Mont Blanc Financial Services
Nicola has spent his career reading the policy wording most people skip, and writes here so you don't discover at claim stage what page 14 meant.
Everything on this blog is written to inform and educate. It is for information only. Nothing here is professional legal, financial, or technical advice. If you are making a significant business decision, speak to a qualified professional first. Mont Blanc Financial Services works hard to keep this content accurate and current, but is not liable for decisions made based on what you read here.